
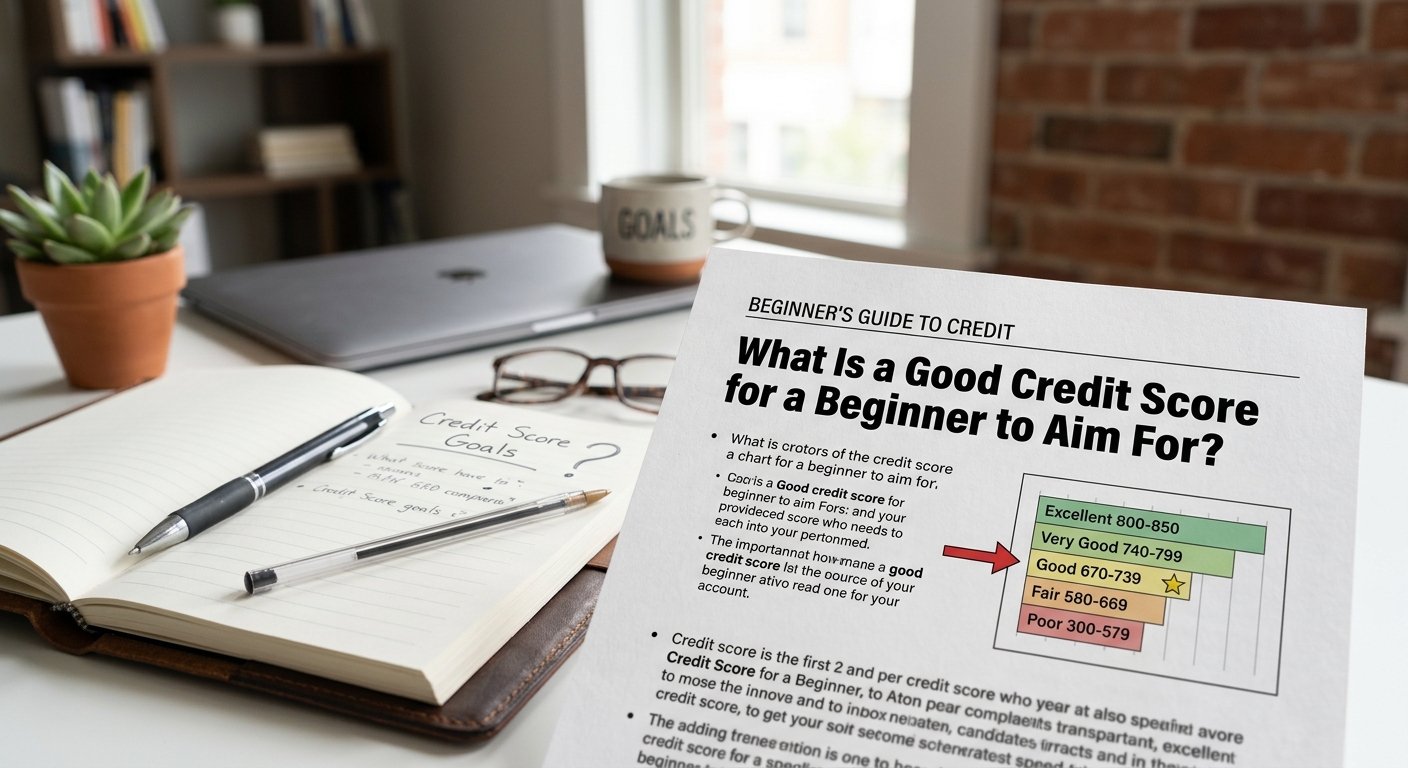
What Is a Good Credit Score for a Beginner to Aim For?
A lot of beginners ask this question expecting a single target number — as if there’s one score that means «you made it.» There isn’t, really. Instead, the more useful way to think about it is: what are you actually trying to qualify for, and what score does that typically require? A score that’s more than enough for one goal can be well short of another.
The Range Ladder, Briefly
Scoring models generally group scores into a handful of tiers — roughly Poor, Fair, Good, Very Good, and Exceptional. However, for the exact cutoffs, and how FICO and VantageScore differ slightly, see our full credit score ranges guide. What matters more than memorizing the boundaries is knowing what each tier actually unlocks in practice, which is where most beginners’ questions really live.
What Is a Good Credit Score for a Beginner, by Goal
Renting an apartment. Many landlords and property management companies look for a score in the low-to-mid 600s as a baseline. However, this varies enormously by market and by property. Some require more; some barely check it at all if your income and rental history look solid.
An everyday unsecured credit card. Most mainstream unsecured cards (not premium rewards cards) approve applicants in the mid-600s and up. Still, some starter cards are specifically designed to approve thinner files in the 600s, or even high 500s.
A decent auto loan rate. Lenders typically start offering meaningfully better rates once you cross into the high 600s to low 700s. Below that, you can usually still get approved, but at a higher interest rate that reflects the added risk from the lender’s side.
A rewards credit card with real perks. Most cards with strong cashback or travel rewards want to see scores of 700+, and the most competitive travel cards often prefer 720–740+.
Mortgage pre-qualification. Many loan programs technically allow scores as low as 580–620. But the best rates are reserved for borrowers in the low-to-mid 700s and above. And mortgage underwriting weighs a lot more than the score alone — income, debt-to-income ratio, down payment, and length of credit history all matter here too.
Notice the pattern: almost none of these require anything close to a «perfect» score. The gap between «good enough to get approved» and «good enough to get the best terms» is usually somewhere in the 670–740 range. That range shows up across nearly every category above.
Why Chasing 850 Isn’t a Useful Goal
It’s common to see 850 treated like a finish line. But it functions less like a goal, and more like a statistical ceiling that almost nobody needs to reach. The practical difference between a 760 and an 850 is minimal — most lenders’ best rates and offers are already available well before that point. Aiming for 850 specifically tends to encourage the wrong behaviors — opening extra accounts, obsessively avoiding any utilization at all. Yet it doesn’t unlock meaningfully better outcomes than a strong, comfortably «Very Good» score already provides.
A Realistic Credit Score Goal for a Beginner (12–18 Months)
For someone starting from zero, a reasonable, evidence-based goal is landing in the 670–740 range within 12 to 18 months of consistent, on-time account management. That’s squarely in «Good» to «Very Good» territory — enough to qualify for most everyday credit, reasonable loan rates, and the large majority of rental applications. It’s an ambitious, but genuinely achievable, target with the habits covered in our guide to building credit from scratch. It’s not a stretch goal that requires unusual luck or aggressive tactics.
Treating «Exceptional» (800+) as a longer-term destination is a more realistic way to frame it than trying to rush there in year one. Instead, think of it as something that develops naturally after several more years of consistent history.
Set Your Target Around What You’re Actually Doing Next
Instead of a generic number, work backward from your actual near-term plans:
- Planning to rent in the next few months? A low-to-mid 600s score is likely already sufficient — don’t delay an apartment search waiting for a much higher number.
- Planning to finance a car within the year? Aim for the high 600s if possible before you apply, since that’s typically where noticeably better rates start to appear.
- Not planning any major application soon? There’s no urgency. Instead, focus on the habits — on-time payments, low utilization — and let the score climb naturally. Don’t optimize for one exact number on one exact date.
Don’t Compare Your Thin-File Score to an Established One
One of the most common sources of unnecessary discouragement is comparing scores that don’t match up. Your six-month-old score isn’t the same thing as a friend’s or family member’s score, built over ten or fifteen years. Length of credit history is a real factor that simply can’t be shortcut. For exactly how that plays out month by month, see our complete timeline guide. A lower score on a new file isn’t a sign you’re doing something wrong. It’s a normal, temporary reflection of how new the file is — not a verdict on your habits.
Frequently Asked Questions
Is 650 a bad credit score for a beginner? No. For someone with only a few months of history, 650 is a completely normal, reasonable point on the way up. It’s not a sign of poor money management — just a reflection of a short file.
How high should my score be before I stop worrying about it? Once you’re comfortably in the «Very Good» range (740+) and consistently managing your accounts, most everyday financial products are fully available to you. At that point, further gains matter less for practical purposes, and more as a general cushion.
Should I delay applying for something until my score is higher? Only if you’re close to a meaningfully better tier, and can reasonably wait. For example, holding off a few months can move you from the high 600s into the low 700s. That can be worth it before a car loan application. Delaying indefinitely in pursuit of a «perfect» score usually isn’t.
Does my target score change once I have an established file? Not really — the same tiers apply throughout your credit life. What changes is how quickly you can realistically move between them. An established file with a long history can often recover from a setback faster than a newer one.
This article is for informational purposes only and is not financial advice. Specific score requirements vary by lender, program, and individual circumstances — the ranges above are general guidance, not guarantees of approval.